In short
Consumer AI is seeing renewed momentum from new assistants and agentic products, but the business model remains weak. Low consumer payment rates and high operating costs are pushing the industry toward enterprise revenue.
- Only a small share of consumers pay for AI services, and average monthly spending is still modest.
- Frontier AI is expensive to run, making consumer subscriptions harder to scale profitably.
- Major players like OpenAI and Meta are leaning more heavily on enterprise and hybrid monetization.
- New assistants may win users, but attention alone does not solve the revenue problem.
Consumer AI is getting better, but the business model still looks fragile: despite flashy new assistants from Meta, OpenAI and others, only a small share of users are paying for AI services and the average monthly spend remains modest. That gap matters because the cost of running frontier AI is still high, pushing many companies toward enterprise customers instead of mass-market subscriptions.
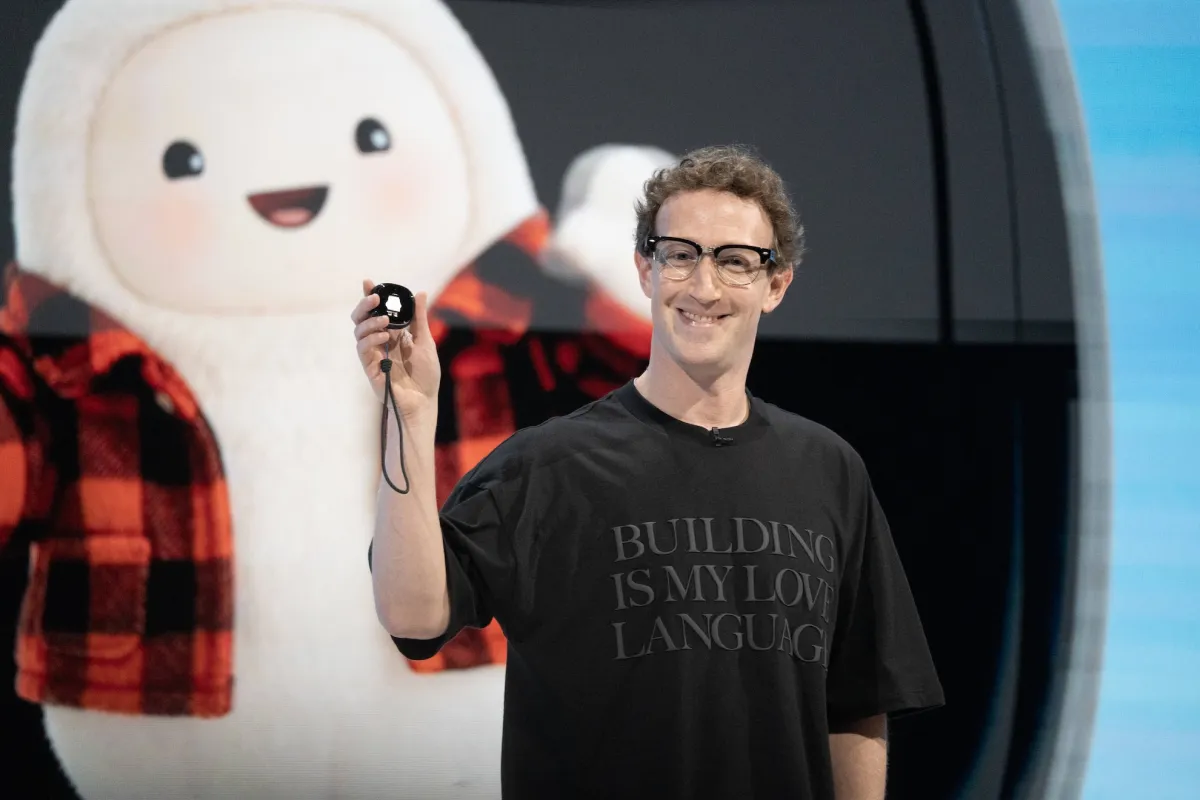
The latest wave of consumer products has revived some optimism. Meta’s Muse assistant and its plush-style companion Jolly have drawn attention, OpenAI has introduced Dots with a similarly playful personal-assistant pitch, and the newly hot Instinct assistant has reportedly reached a $10 billion valuation on the promise of handling everyday errands. But underneath the buzz, the economics remain stubbornly difficult.
The comeback story has a catch
For much of the past year, the consumer side of AI looked like a disappointment waiting to happen. The technology was impressive, but the market reality was sobering: people liked trying AI tools, yet relatively few were willing to pay much for them. That dynamic has not disappeared, even as models and products have improved.
The renewed excitement comes from a simple idea: agentic AI has become reliable enough to do practical things for ordinary users. Booking a dinner table, finding a flight, canceling a subscription, or managing routine digital errands are all tasks that can feel genuinely valuable if they are handled without friction. Investors are hearing echoes of the early ChatGPT moment, when a new capability appeared suddenly and opened a product category that did not seem viable before.
Yet the commercial challenge is different from the technical one. A product can be beloved, widely used and culturally visible without becoming a strong standalone business. That tension is now defining the consumer AI market.
How much are consumers actually paying for AI?
They are paying less than bullish headlines might suggest. Several recent market snapshots point to slow adoption and modest spending, even as awareness rises.
Andreessen Horowitz’s semiannual State of Markets report, which drew on a PNC research study from earlier this year, showed that by May 2.2% of consumers were paying for AI services. Those paying users spent an average of $31 a month. The venture firm presented that as evidence that adoption is still early-stage, but the charts also showed a frustratingly gradual pace of change.
In other words, model quality may be advancing quickly, but the willingness of consumers to open their wallets is moving far more slowly. The charted gains appear almost linear rather than explosive, which is a warning sign for businesses that need rapid revenue growth to justify large infrastructure and training bills.
Another data point comes from Bank of America, which reported in March that about 3% of U.S. consumers were paying for AI, up 40% from the year before. That is growth, but from a very small base. Meanwhile, a Menlo survey from September offered a more optimistic picture, finding that one quarter of adults use AI every day and that half of those daily users pay for it. Even there, however, the market is still far from the kind of broad conversion rates that support a high-margin consumer subscription giant.
Why the economics look so difficult
The core problem is not demand alone; it is cost. AI is unusually expensive to run compared with many earlier digital products, especially consumer services built on advertising or lightweight cloud infrastructure.
Traditional consumer internet businesses often benefit from a low marginal cost per user. A social network can serve another user relatively cheaply once the platform is built. AI is different. Every additional prompt, image generation, voice interaction or agentic task consumes compute, and that compute has a real cost attached to it. Even a large paying user base may not be enough if the infrastructure bill scales too quickly.
The arithmetic becomes more uncomfortable when you compare consumer AI to mature subscription businesses. If a company reached the scale of a streaming giant with 325 million subscribers and each user paid around $34 a month, that would still produce about $11 billion in annual revenue. For a frontier AI company, that is not necessarily enough to cover operating costs, particularly when model training, inference, research and product expansion are all included.
This is why consumer AI has become a harder bet than many assumed. The products may be easier to imagine than enterprise software, but they are not automatically easier to monetize.
| Metric | Latest figure | What it suggests |
|---|---|---|
| Consumers paying for AI | 2.2% in May | Adoption remains narrow |
| Average monthly spend | $31 per user | Revenue per customer is still modest |
| Bank of America estimate | About 3% of U.S. consumers paying | Growth exists, but from a low base |
| Menlo survey finding | 25% of adults use AI daily | Usage is broader than payment |
| Enterprise signal from OpenAI | Bookings reportedly doubled since July | Business customers are becoming the main revenue engine |
What changed since ChatGPT’s breakout?
The product market changed faster than the revenue model. The original ChatGPT boom convinced many companies and investors that consumer AI could be the next great platform shift, but the economics never matched the scale of the excitement.
When ChatGPT first exploded in 2022, it seemed to point to a future in which millions of people would pay for access to smart assistants the way they pay for streaming, cloud storage or mobile apps. That assumption turned out to be too simple. AI users may be enthusiastic, but they do not necessarily behave like loyal subscription customers, and the price they are willing to pay has not risen nearly as fast as model capability.
That mismatch helps explain the broader strategic shift across the industry. Rather than building around consumer subscriptions alone, many leading AI firms are leaning into enterprise contracts, workflow tools and vertical-specific deployments. In practice, that means selling AI where it can be tied directly to business productivity, compliance, and revenue generation.
Anthropic’s business strategy is a useful example of this pivot. The company has been widely seen as a model for enterprise-first growth, focusing on business relationships and industry-specific use cases instead of relying primarily on consumer-scale monetization. As that path has gained credibility, others have followed in one form or another.
Why are the biggest labs moving toward enterprise?
Because enterprise customers are easier to monetize at scale. Businesses pay more predictably, sign larger contracts and often use AI in ways that justify premium pricing.
For AI labs, enterprise revenue has a second advantage: it helps offset the immense cost of providing consumer-facing products. A consumer can ask a chatbot a few questions and pay little or nothing. A business may pay thousands or millions of dollars for secure access, custom integrations, admin controls and domain-specific deployment.
That is why the consumer model has increasingly become a funnel rather than an end state. A widely used personal assistant can create brand familiarity, gather user data, and prove technical capability, but the real economics may come from enterprise licensing, API sales or embedded workflows.
OpenAI appears to have embraced that logic. Its enterprise push has reportedly been working well, with bookings said to have doubled since July. Even the company’s consumer-facing Dots launch was framed with a business angle, including possible usefulness for software engineers and agency teams. In other words, the product may look playful on the surface while still serving a deeper business-sales strategy underneath.
Andreessen Horowitz argued that AI adoption is still “early” and that there is plenty of room for consumer growth, but the data in its own charts shows how gradual the shift in paying behavior still is.
How are Meta, OpenAI and Instinct trying to escape the trap?
They are using different monetization paths, but each faces the same basic cost pressure. The companies are trying to make consumer AI feel useful enough to support a business, even if the business eventually depends on other revenue sources.
Meta’s advantage: ads and scale
Meta may have more room than most because it already operates one of the world’s most effective advertising systems. If Muse becomes a meaningful personal assistant, Meta can connect that usage to its broader targeting and ad infrastructure. That gives the company options beyond direct subscription revenue.
Meta is also exploring enterprise opportunities, suggesting it may not want to rely solely on consumer willingness to pay. A consumer assistant backed by ad tech can afford to be more experimental than a company that depends entirely on monthly subscription revenue.
OpenAI’s strategy: consumer appeal, enterprise discipline
OpenAI’s path looks more balanced between consumer brand power and business monetization. The company still launches consumer products that capture attention, but its enterprise traction appears increasingly central to its financial story. That matters because it reduces reliance on the uncertain economics of individual user subscriptions.
In practical terms, a consumer product can still serve as a top-of-funnel acquisition tool. If a user likes the assistant enough to pay, great. If not, the company can still benefit from awareness, usage data and downstream business adoption.
Instinct’s approach: transactions and commissions
Instinct is trying a different path altogether. Rather than relying only on subscriptions, it reportedly plans to take a cut of purchases routed through the assistant. That model could expand the revenue ceiling if users really do start delegating travel, reservations and shopping tasks to AI agents.
The company may also avoid one of the biggest cost burdens facing frontier labs: training a foundation model from scratch at the bleeding edge. If so, it may have a better chance of aligning expenses with revenue, though it will still need to prove that consumers trust AI agents with real-world actions.
What does the adoption data really mean?
It means usage is broader than payment, but payment is what determines long-term survival. Many people are experimenting with AI every day, yet only a small fraction are converting into recurring paying customers.
That distinction is crucial. Daily use signals habit, familiarity and potential future demand. But a product company cannot pay data-center bills with casual engagement alone. Revenue needs to be durable, and the consumer market has not yet shown that it can support frontier-scale spending.
The figures from PNC, Bank of America and Menlo are not perfectly comparable because they measure slightly different things in different populations, but they point in the same general direction: AI has become normalized, yet monetization remains limited. The market is bigger than it was a year or two ago, but not big enough to make consumer AI an easy win.
Who stands to benefit most if consumer AI stays limited?
Enterprise AI vendors, infrastructure providers and companies with existing monetization systems are likely to benefit most. If consumers remain reluctant to pay, the winners will be firms that can attach AI to business spending or existing revenue streams.
That means the strongest positions may belong to companies that already have one or more of the following advantages:
- a large enterprise sales organization
- an existing subscription or software business
- an advertising machine that can subsidize consumer usage
- direct control over a high-value workflow, such as coding, customer support or procurement
- access to massive compute resources that make it easier to absorb low-margin usage
By contrast, pure consumer startups face a harder path. They may generate excitement quickly, but without a clear way to convert that excitement into cash, they risk becoming expensive experiments.
Why investors still care
Because the upside remains enormous if one company can crack the model. Consumer AI still looks like a category capable of producing massive products and huge audiences, even if the economics are messy today.
Investors are attracted to the same logic that once fueled the rise of search, social media and mobile ecosystems: a new interface layer can reshape how people interact with technology. If AI assistants become the primary way people manage information, tasks and purchases, the winner could own an extraordinarily valuable user relationship.
That is why the market still assigns eye-catching valuations to promising assistants, even after repeated reminders that monetization is hard. The opportunity is too large to ignore. But the gap between product appeal and revenue reality is wide enough that many founders may ultimately need to rethink what business they are actually in.
How this could evolve from here
The likely path is a hybrid one, not a consumer-only one. The most successful AI companies may keep building products for individuals while depending on businesses, transactions or platform fees to make the economics work.
That could mean a few different future states:
- Consumer assistants become the front door to larger enterprise platforms.
- Agents earn money by taking a commission on completed purchases or bookings.
- Ad-supported models absorb consumer usage while businesses pay for premium versions.
- AI becomes a feature inside broader software ecosystems rather than a standalone subscription.
Any of those models would be more plausible than a pure “everyone pays a premium monthly fee” approach. The market has already signaled that it wants AI tools to feel valuable, but not necessarily expensive.
For now, that leaves consumer AI in an awkward position: popular enough to attract major bets, but not yet profitable enough to justify those bets on its own.
The bottom line
Consumer AI may be improving quickly, but the business still does not pencil out cleanly. Small payment rates, modest average spending and enormous operating costs are forcing the industry to rethink what success looks like.
Meta, OpenAI and Instinct may each be testing different paths to monetization, but they are doing so against a structural problem that has not gone away. AI can now do more for ordinary people than it could a year ago. The question is not whether the products are useful. It is whether enough people will pay enough money, consistently, to support the cost of making them.
So far, the answer remains uncertain. That uncertainty is why the sector’s most optimistic consumer stories are still being overshadowed by the same old lesson: in AI, attention is easy to win, but revenue is still hard to earn.
Frequently asked questions
Why is consumer AI still hard to monetize?
Consumer AI is still hard to monetize because relatively few users pay for it and the average monthly spend is low, while the cost of running frontier models is high. That combination makes it difficult for companies to scale profitably on subscriptions alone.
How many consumers are paying for AI services?
Only a small share are paying. One recent market snapshot showed 2.2% of consumers paying for AI in May, with average monthly spending of about $31. Another estimate from Bank of America put the figure near 3% of U.S. consumers.
Why are AI companies shifting toward enterprise customers?
AI companies are shifting toward enterprise customers because businesses pay more predictably, sign larger contracts and are easier to sell premium features to. Enterprise revenue can help offset the high cost of training and serving frontier AI models.
What makes Meta’s AI strategy different from OpenAI’s?
Meta has a major advantage because it can combine consumer AI with its advertising business, giving it more monetization options. OpenAI appears to rely more on a mix of consumer products and enterprise bookings to improve the economics of its AI business.
Can consumer AI still become a huge business?
Yes, but likely not as a pure subscription market. The most plausible path is a hybrid model that combines consumer usage with enterprise contracts, transaction fees, advertising or platform partnerships.